City guides
City guides (435)
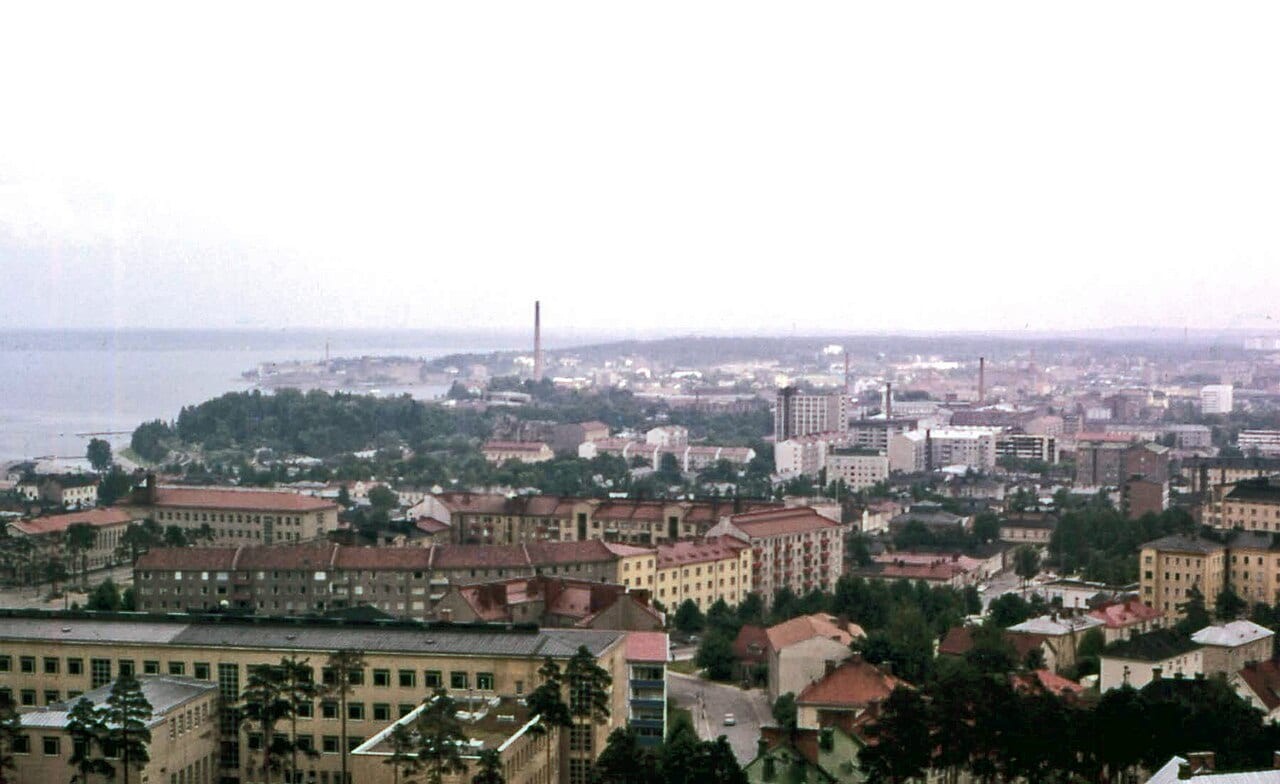

Tampere City Guide
Finland
Finland’s third-largest city and the fastest-growing urban centre in the country, Tampere has transformed from a 19th-century textile-mill town into a university and technology hub set between two lakes. For investors the appeal is demographic and infrastructural: the Tampere city region adds roughly 5,000 new residents a year and is projected to reach half a million by 2040, while the new tram line, which opened its first routes in 2021, has unlocked tens of thousands of planned homes along its corridor. Entry prices are accessible by Nordic standards, with apartments ranging roughly €2,100–3,800 per square metre and a citywide average near €4,100/m² for newer stock, well below Helsinki. The student-heavy Hervanta district, fed by Tampere University and on the tram line, delivers gross yields around 5.5–6.5%, against a Finnish national average near 5.6%. The national backdrop is mixed: Finnish prices drifted down roughly 2–3% year-on-year into early 2026 after a soft patch, but a recovery of about +2.5% is forecast for 2026 as rates normalise and construction stays near historic lows. With migration-driven demand outpacing new supply in growth cities, Tampere combines among the most attractive yields in the Nordics with a clear long-run growth narrative.
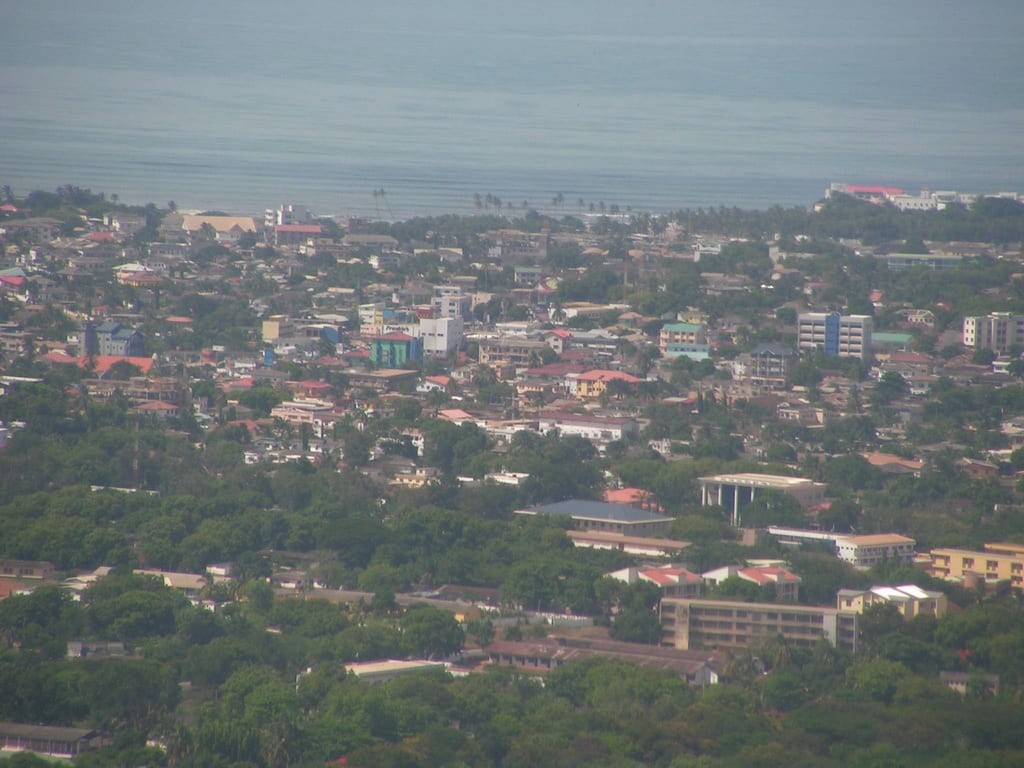

Accra City Guide
Ghana
Accra is Ghana's capital and the commercial heart of West Africa's most dynamic real-estate market, a coastal metro of roughly 2.8 million on the Gulf of Guinea. The prime residential map is concentrated in a tight cluster of established neighbourhoods, Airport Residential Area, Cantonments, East Legon, Labone, and Dzorwulu, where expatriate and corporate demand keeps vacancy as low as 3-5%. In these districts, prime three-bedroom houses run roughly USD 450,000-600,000 and high-end apartments USD 250,000-400,000, with East Legon stock spanning USD 350,000 to well over USD 1 million at the top tier. Greater Accra prices grew an estimated 7-12% in nominal cedi terms over the past year, and gross rental yields range widely from about 6.5% to 9.5% depending on segment, generally 7-8% for serviced apartments on long leases in Airport Residential. The 2026 market is bifurcated: mid-market gated homes (USD 80,000-350,000) absorb quickly at firm prices, while the luxury segment above USD 400,000 is a buyer's market with oversupply and negotiating room of 10-20%. Dollar-denominated demand and cedi volatility are defining features for international buyers.
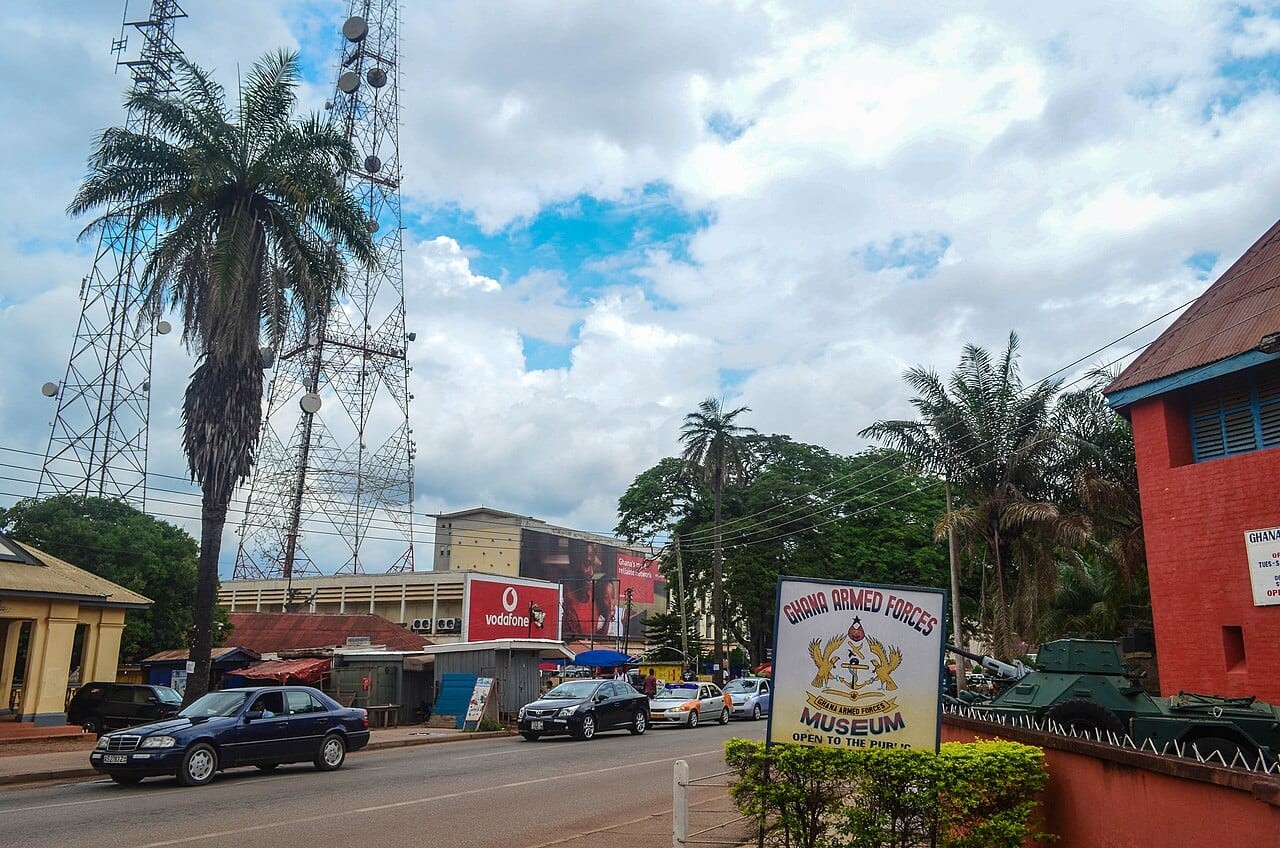
Kumasi City Guide
Ghana
Kumasi is Ghana's second city and the capital of the Ashanti Region, the historic seat of the Asante kingdom and a fast-growing commercial and logistics hub serving the country's interior. Its metropolitan area numbers around 3.5 million people and is expanding at roughly 3.6% a year, with projections approaching 4.8 million by 2031, demographic momentum that sits at the centre of its property investment case. Kumasi is markedly more affordable than Accra: three-bedroom homes average around GHS 1.2 million (about USD 80,000), rising to USD 180,000-250,000 for prime stock in upmarket districts such as Nhyiaeso, Ahodwo, and Asokwa. Prices climbed about 5% in 2024 and are forecast to grow 5-10% annually over the next five years, driven by infrastructure, urban expansion, and rising investor interest. The trade-off for lower entry prices is higher income: gross rental yields run roughly 8-12%, with the strongest returns in affordable and student housing near the Kwame Nkrumah University of Science and Technology (KNUST). Those upper-end yields reflect emerging-market and cedi-currency risk rather than guaranteed returns, but they position Kumasi as Ghana's leading value-and-yield alternative to the capital.
Takoradi City Guide
Ghana
Capital of Ghana's Western Region and the commercial half of the Sekondi-Takoradi twin city, Takoradi is the country's oil-and-gas gateway, its deep-water port dredged from 11 to 16 metres over the past decade to rival Tema and to service the offshore Jubilee and TEN fields. Property demand has tracked the energy build-out, with three-bedroom homes in prime Beach Road, Chapel Hill and Windy Ridge running roughly USD 120,000-180,000 and serviced residential plots between USD 60,000 and USD 110,000. Foreign buyers face Ghana's constitutional ceiling on tenure: non-citizens cannot hold freehold and are limited to leaseholds of up to 50 years, renewable, while Ghanaian citizens may hold 99-year leases. Rental yields are healthy by Western standards at roughly 6-8% gross on serviced expatriate-grade housing, though non-resident landlords pay a 15% withholding tax on rental income and contend with cedi depreciation against the dollar.
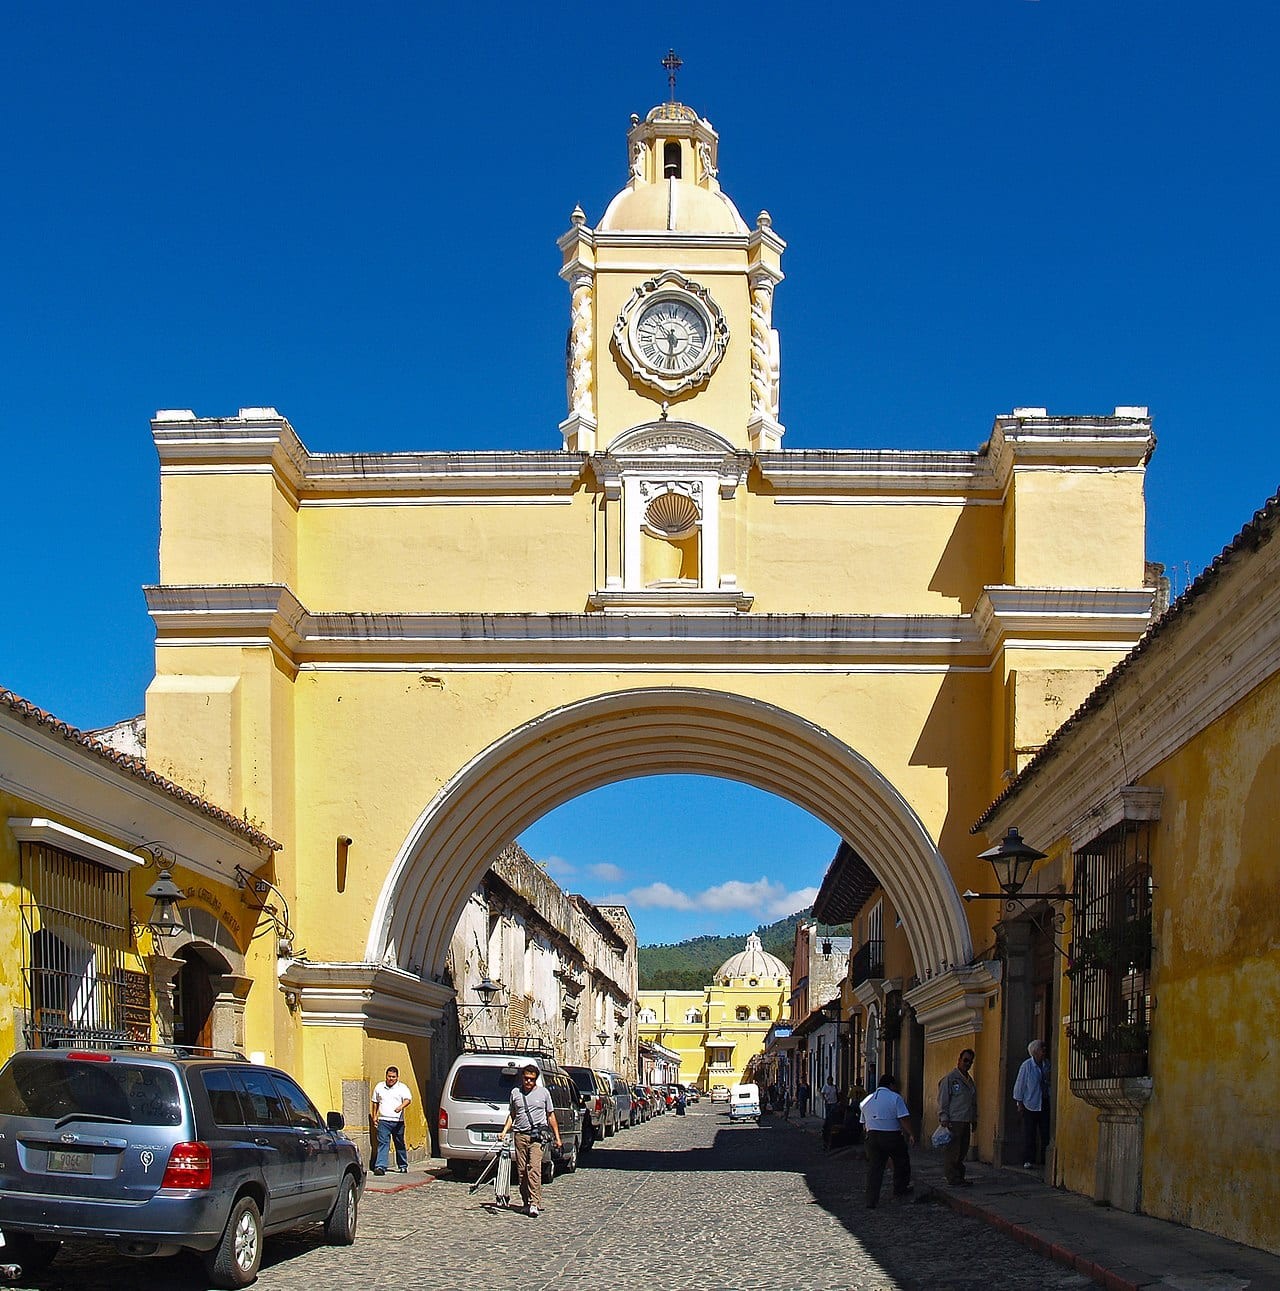

Antigua Guatemala
Guatemala
Antigua Guatemala, a UNESCO World Heritage colonial city ringed by three volcanoes, is the country's premier lifestyle and short-term-rental market. Cobblestone streets, restored Spanish-Baroque casas, and a thick concentration of expats, language students and tourists keep occupancy high year-round. As of 2026, restored homes inside the historic core trade at roughly USD 3,400-5,200 per m2 (about USD 320-500 per sqft), with mid-market family homes in surrounding aldeas at USD 1,200-2,200 per m2. Antigua leads national appreciation at 5-8% YoY, ahead of the country's 4-6% average, driven by strict heritage rules that cap new supply. Gross rental yields run 6-8% on long lets, but well-managed Airbnb properties frequently clear 8-12%. Foreigners may own freehold here outright (Antigua sits far from any restricted border, coastal or lake strip), buying on a tourist visa with a passport and NIT tax number. Closing costs run roughly 3-4% (1.5% transfer tax, notary and registry), with annual IUSI property tax near 0.9% of assessed value. Guatemala offers no property golden visa, but the Decree 44-2016 investor residency (up to 5 years) suits buyers seeking a base. Limited mortgage access means most foreign purchases are all-cash.
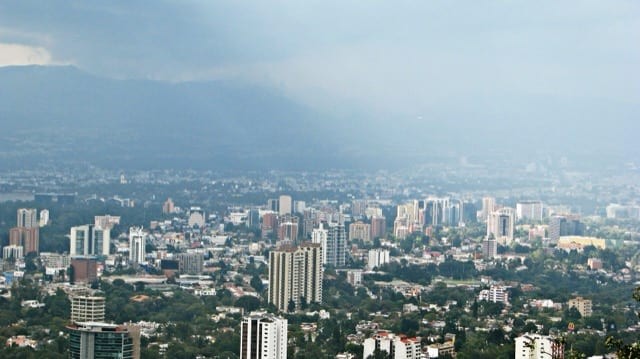
Guatemala City
Guatemala
Guatemala City is Central America's largest metropolis and the country's commercial and financial engine, anchoring a metro population of roughly 3.2 million. Demand from professionals, embassy staff and corporate expats concentrates in the upscale southern zones, where 2026 asking prices reach Q14,000-28,000 per m2 (about USD 1,800-3,660), with Zona 14 the priciest. The city posts the steadiest growth in the country at 4-6% YoY, underpinned by urbanization now above 67% and a expanding middle class. Gross rental yields of 5.7-8.4% in the prime zones are among Latin America's healthiest, with furnished apartments in Zona 10 and 14 renting at Q8,000-15,000+ monthly. Foreigners enjoy full freehold rights here, the capital sits clear of any restricted border, coastal or lake zone, and may buy on a tourist visa with passport and NIT; closing costs run 3-4%. Mortgage financing for non-residents is scarce, so purchases are typically all-cash. The Decree 44-2016 investor-residency route (up to five years) appeals to those wanting a regional base; Guatemala has no property-linked golden visa.
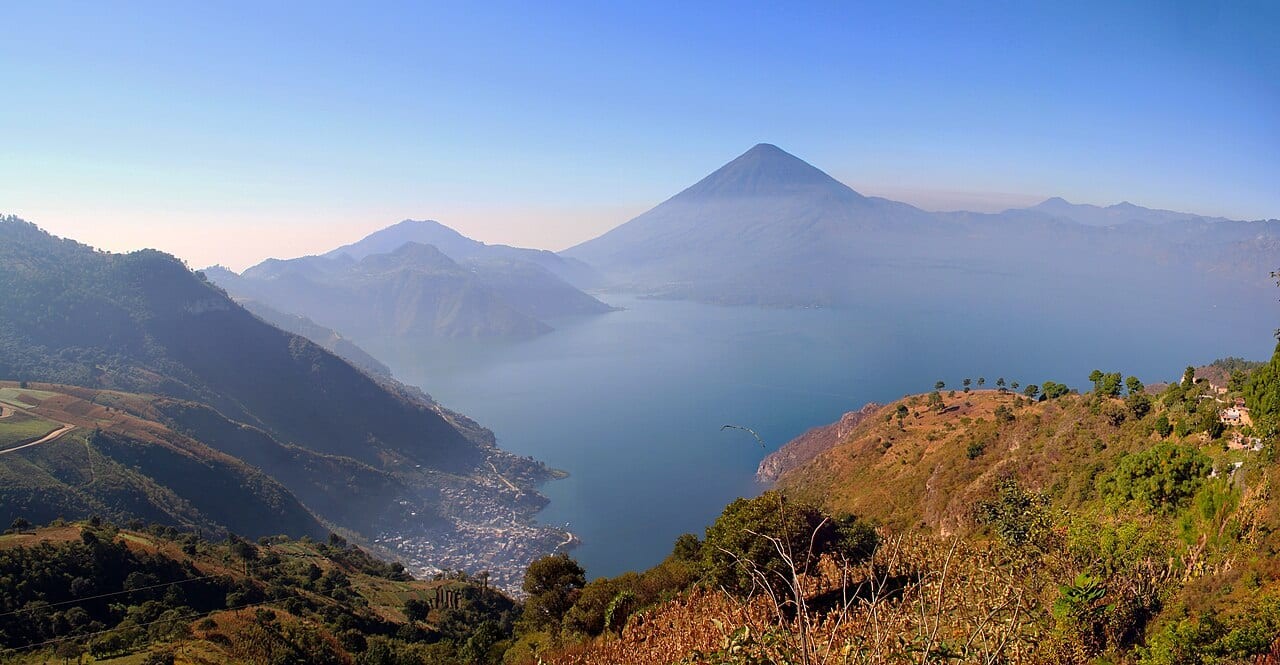
Panajachel
Guatemala
Panajachel ('Pana') is the gateway and expat hub of Lake Atitlan, a volcanic-crater lake ranked among the most beautiful in the world. It is the only lakeside town with reliable road access, a bus terminal, major-bank ATMs, hospitals and a large market, making it the lake's most convenient and liquid property market. Roughly 15,000 residents include a dense international community. Lakefront and lake-view homes start around USD 100,000 and rise past USD 500,000 for prime waterfront, with vacation rentals earning Q8,000-30,000 monthly (USD 1,000-3,900) and gross yields of 8-12% for well-run short-term lets. A critical caveat: Guatemalan law bars foreigners from directly owning land within 200 m of a lake shore, so true lakefront is held through a Guatemalan corporation (Sociedad Anonima), while many hillside lake-view lots beyond the 200 m strip can be owned freehold outright. Inland and view properties carry standard 3-4% closing costs and ~0.9% annual IUSI tax. Demand is lifestyle-driven, retirees, remote workers and tourism, and supply is constrained by terrain, supporting steady appreciation in the 4-7% range.
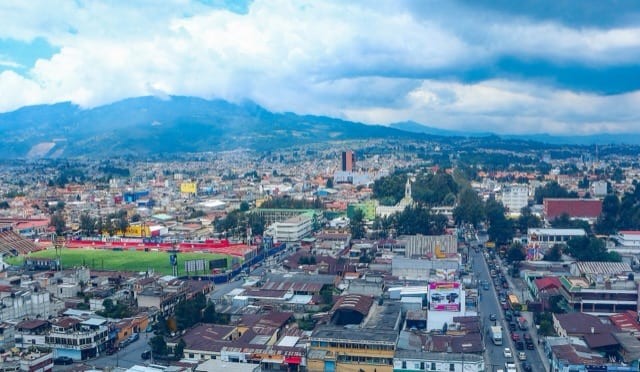
Quetzaltenango
Guatemala
Quetzaltenango, universally known as Xela, is Guatemala's second city and the commercial and educational anchor of the western highlands. At 2,330 m it has a cool climate, a handsome neoclassical centre around Parque Centro America, universities, hospitals and the country's best street food, all at a fraction of Antigua or capital pricing. A single expat lives comfortably on USD 700-1,100 a month; Xela runs roughly 25% cheaper than Antigua and 50% below the capital's upscale zones. Resale colonial casas and condominiums trade 20-35% below new-build cost, with prices broadly in the USD 700-1,400 per m2 range, well under the country's tourist hotspots. Foreigners can own titled real estate directly and freehold here (Xela sits far inland, clear of any border, coastal or lake restriction), buying with a passport, NIT and a bilingual attorney for a cadastral title search. Closing costs run about 3-4% (1.5% transfer tax) and annual property tax around 0.8% of assessed value. Long-term rental demand from students, professionals and a steady expat-and-language-school community underpins gross yields of 6-8%, with appreciation in the 4-6% range.
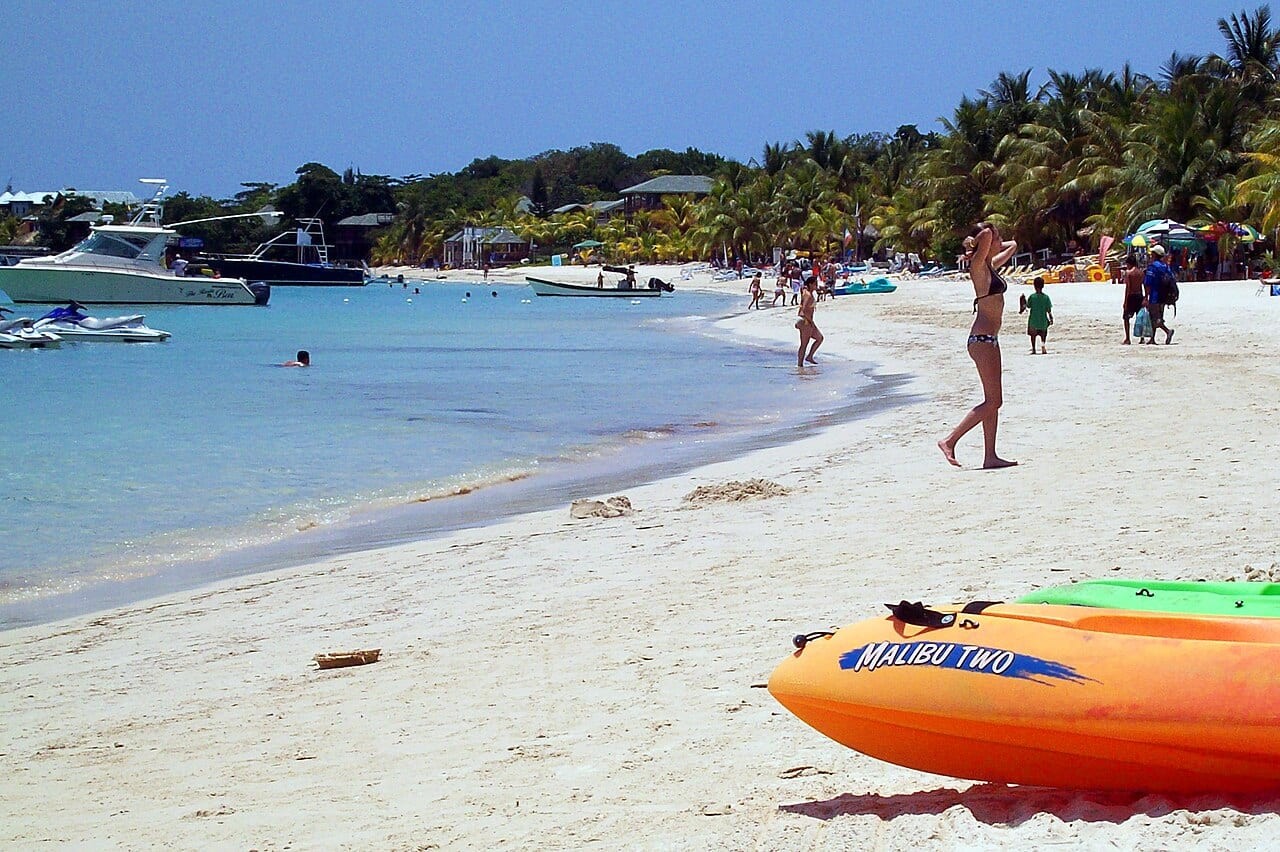

Roatán
Honduras
Roatán is Honduras's flagship Caribbean property market and the largest of the Bay Islands, drawing North American and European buyers with world-class diving on the Mesoamerican Reef, cruise-ship tourism, and full US-dollar pricing. In 2026 the island average sits near US$500,000, with beachfront homes opening around US$750,000 and luxury estates topping US$1 million; condos remain the accessible entry point at roughly US$228,000 (1-bed) to US$323,000 (2-bed). Prime West Bay beachfront commands US$4,500-US$7,500 per m², while Oak Ridge and Punta Gorda run US$1,200-US$2,500 per m². Prices rose 4-7% in USD terms over the past year, and gross rental yields range from 4-7% on premium West Bay beachfront to 7-12% in higher-yielding pockets, with well-managed short-term rentals achieving 60-75% annual occupancy and US$2,000-US$4,000 weekly in peak season (December-April). Foreign ownership is straightforward: Decree 90-90 lets a foreigner directly hold one urban property up to 3,000 m², while a Honduran corporation removes size and quantity limits and is the standard structure for larger or beachfront coastal acquisitions. Annual property tax is low at roughly 0.35% of assessed value. Honduras is not dollarized, but Roatán transacts almost entirely in US dollars, insulating investors from lempira volatility.
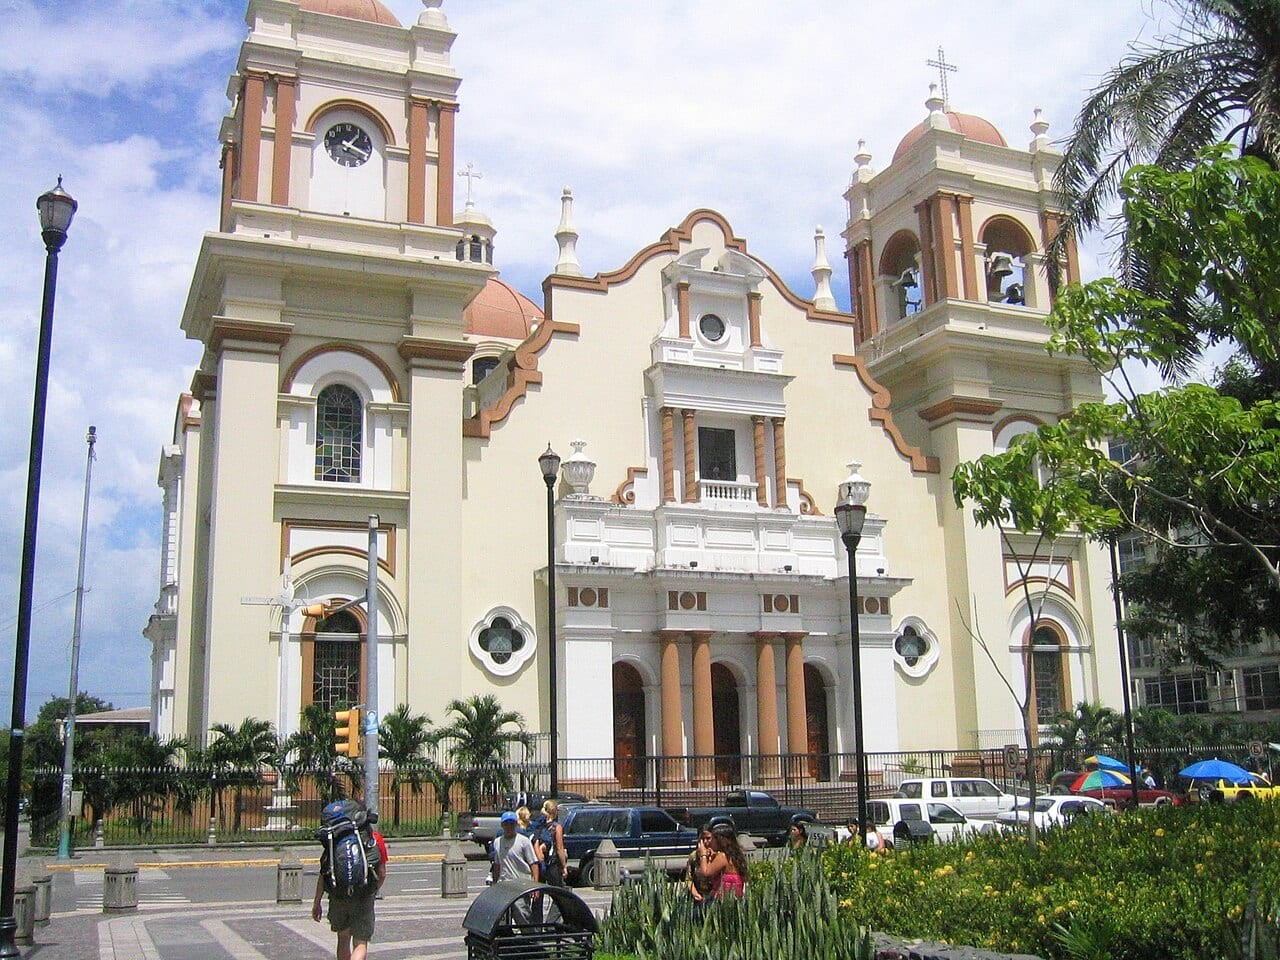
San Pedro Sula
Honduras
San Pedro Sula is Honduras's industrial and commercial capital and the economic engine of the country's north, anchoring the Cortés manufacturing corridor and Puerto Cortés, Central America's busiest container port. Its 2025 population reached about 1,034,000, growing 2.58% annually toward roughly 1,060,000 in 2026. This is a yield-driven domestic market rather than a dollar-priced resort one: apartments average about US$2,400/m² and houses around US$1,480/m², with city-center and upscale zones spanning US$600-US$1,200/m². The median residential price runs L3,190,000-L3,650,000 (roughly US$130,000-US$150,000), and two-bedroom apartments trade at US$89,000-US$110,000. Prices are rising 3-7% annually on industrial expansion and urban development. Rental yields are the strongest on the Honduran mainland: Colonia Trejo delivers about 7.0% net, and the central cluster of Trejo, Río de Piedras, and Jardines del Valle sustains 90%+ one-bedroom occupancy, the highest in the national dataset. Average rent is around L240/m²/month (about US$9), ranging L180-L320 by area, with 2026 rent growth projected at 4-6%. Honduras is not dollarized, so mainland investors carry lempira exposure, though rents and many sale prices reference USD. Foreigners may own under Decree 90-90 (one urban property up to 3,000 m²) or via a Honduran corporation; mainland urban property is unrestricted, unlike the coastal/border zones.
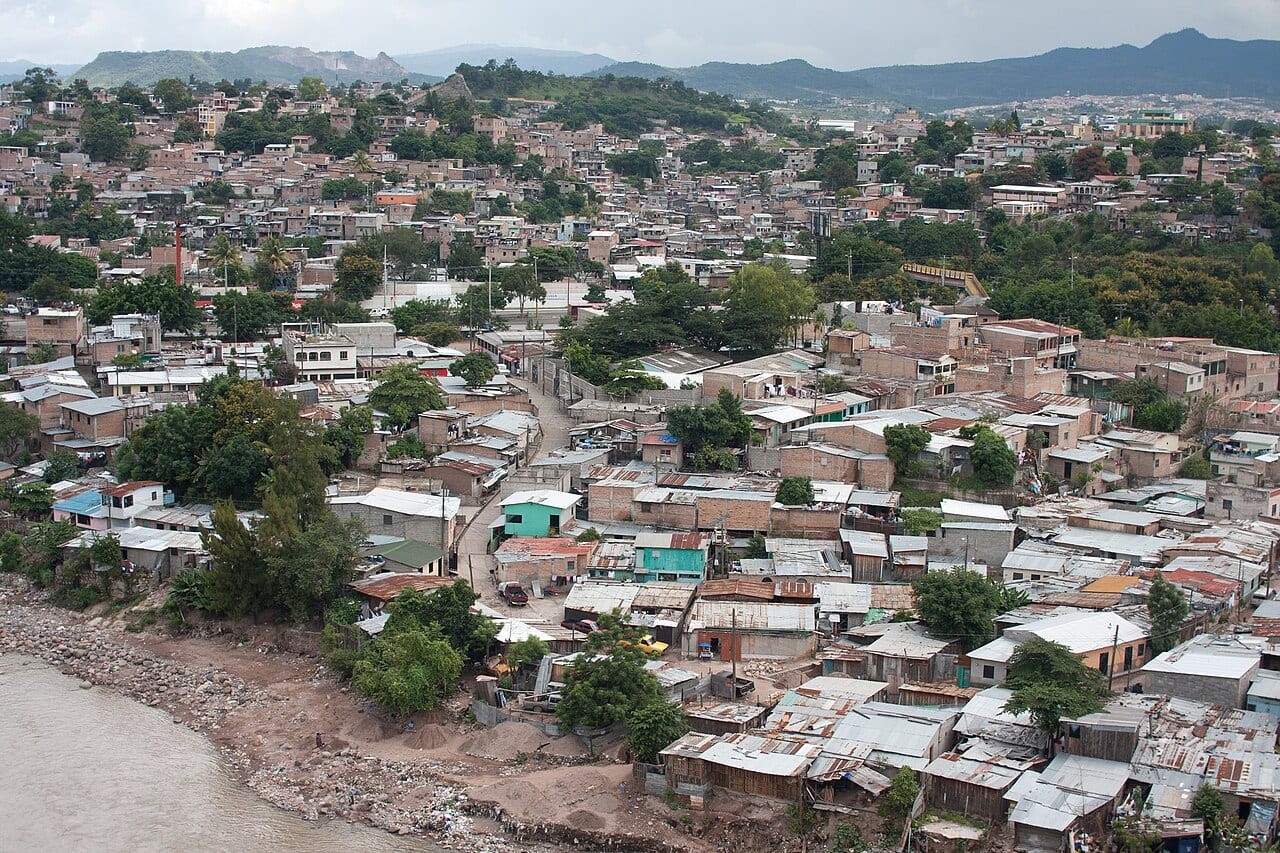
Tegucigalpa
Honduras
Tegucigalpa is Honduras's capital and largest metropolitan area, the seat of government, embassies, NGOs, and the country's administrative economy. Its 2026 population is estimated near 1,691,030, growing 2.47% annually. As the primary domestic job market, it is a yield-and-stability play rather than a dollar-priced resort market. Prime apartments command around US$2,500/m², with the highest prices in Lomas del Guijarro, Palmira, and El Hatillo (roughly L35,000-L55,000/m²), while budget peripheral areas start near HNL 9,000/m² (about US$340). The 2026 median housing price is about L5,800,000 (roughly US$220,000). Rental demand is anchored by government employees, NGO and embassy staff, and professionals: a 2-bedroom apartment averages about L31,250/month (around US$1,250). The highest gross yields are in Miraflores (6.5-8.5%) and Colonia Kennedy (7-10%), with Boulevard Los Próceres at 5.5-7.5% and Colonia Palmira at 5-7%. Lomas del Guijarro and Lomas del Mayab lead appreciation at 8-10% annually, though citywide nominal growth of about 5% nets near 0-1% after inflation. Honduras is not dollarized, so investors carry lempira exposure. Foreigners may own under Decree 90-90 (one urban property up to 3,000 m²) or through a Honduran corporation; the capital is inland and unrestricted, unlike coastal/border zones.
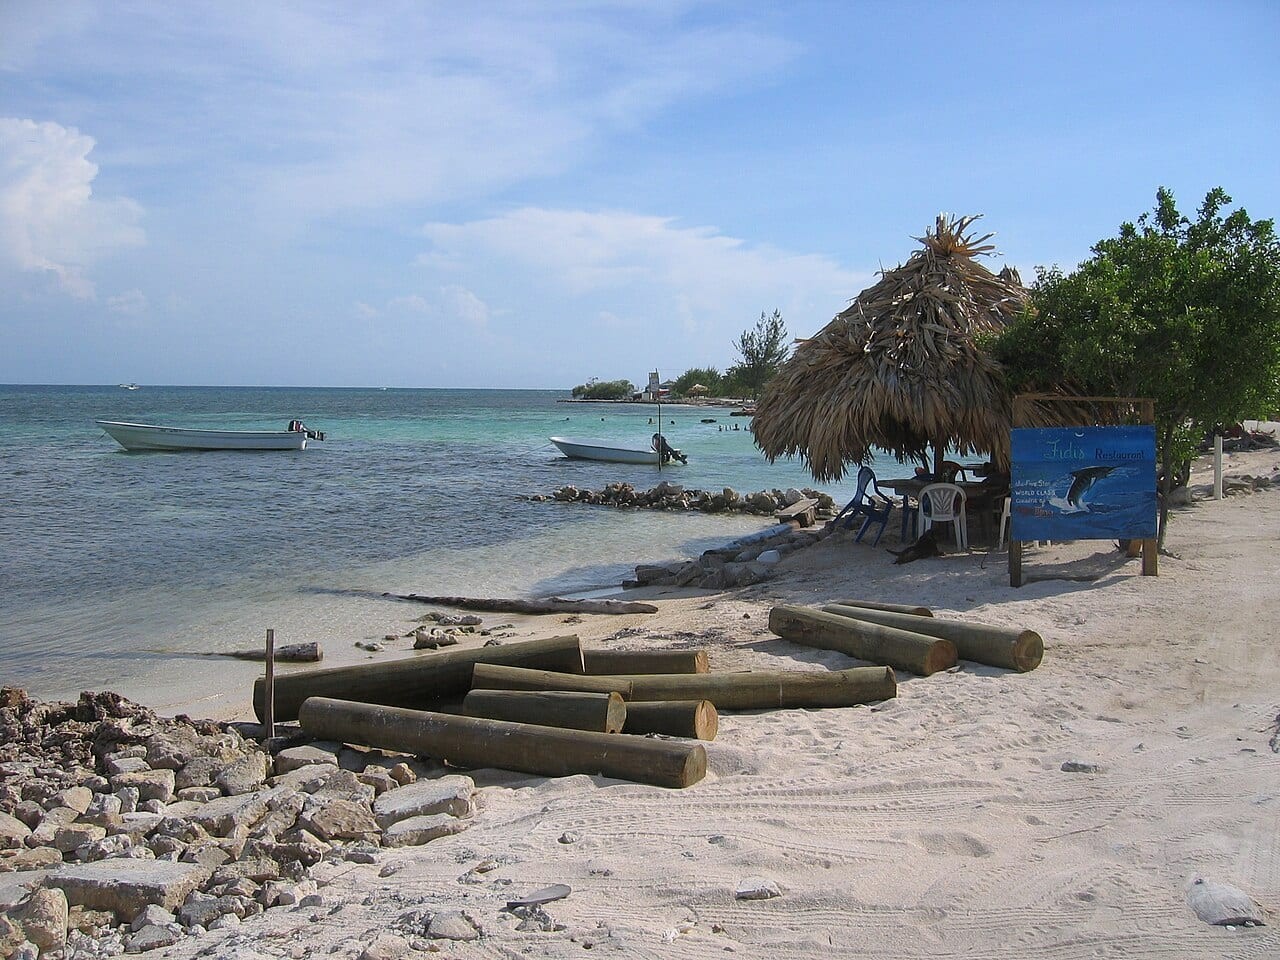
Utila
Honduras
Utila is the smallest and most affordable of the three main Bay Islands, world-famous as a budget scuba-diving and whale-shark destination and a long-standing backpacker hub. It offers the lowest entry point in Honduras's Caribbean island market: the median property price is roughly US$59,800 with a median of about US$24 per sqft, while houses carry a median near US$359,000 (about US$1,924 per m²). Vacant lots start around US$30,000, and Bay Islands properties broadly span US$85,000-US$469,000. The market is thinner and more cash-driven than Roatán, so liquidity is lower and days-on-market longer, but the dive economy underpins consistent seasonal rental demand. Like Roatán, Utila prices and transacts in US dollars even though Honduras is not dollarized. Foreign ownership follows the same national framework: Decree 90-90 permits direct foreign ownership of one urban property up to 3,000 m², and a Honduran corporation is used for larger holdings and coastal parcels. Property tax is low at roughly 0.35% of assessed value. Investors typically target dive-shop-linked guesthouses, beachfront lots on the south shore, and town homes around East Harbour, where most services, dive operators, and rental demand concentrate. Yields on well-run dive-tourism rentals run roughly 6-9% gross.
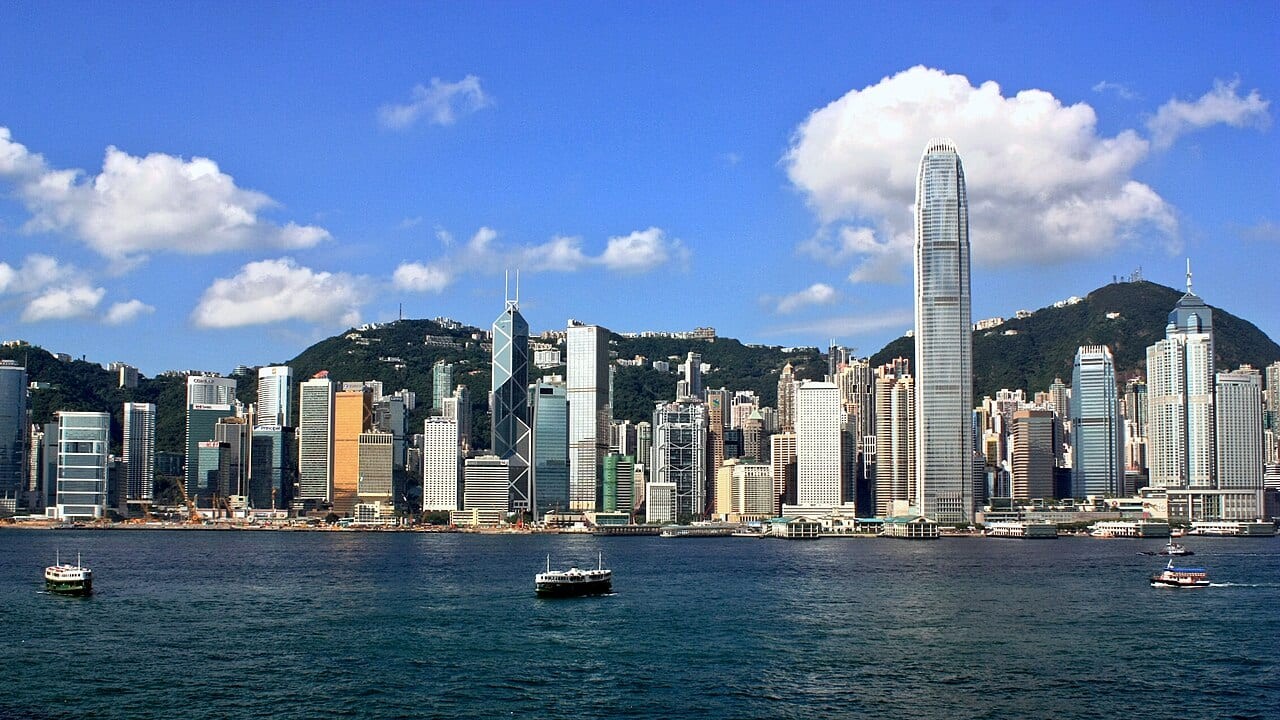

Hong Kong City Guide
Hong Kong
Hong Kong is a global financial hub and one of the world's most expensive residential markets, with prime districts among the priciest real estate on earth. Its currency is pegged to the US dollar at ~7.8, giving USD-based investors near-zero FX risk and making it a perennial safe-haven for capital. After a roughly 28–30% correction from the 2021 peak, prices bottomed in mid-2025 and have risen since, with institutional forecasts pointing to modest further growth. Crucially, in February 2024 Hong Kong abolished all extra demand-side stamp duties, so non-resident and additional-home buyers now pay only the normal ad valorem duty, materially lowering the cost of entry. Yields remain structurally low (~2–3.5%), so the thesis is capital and currency stability.
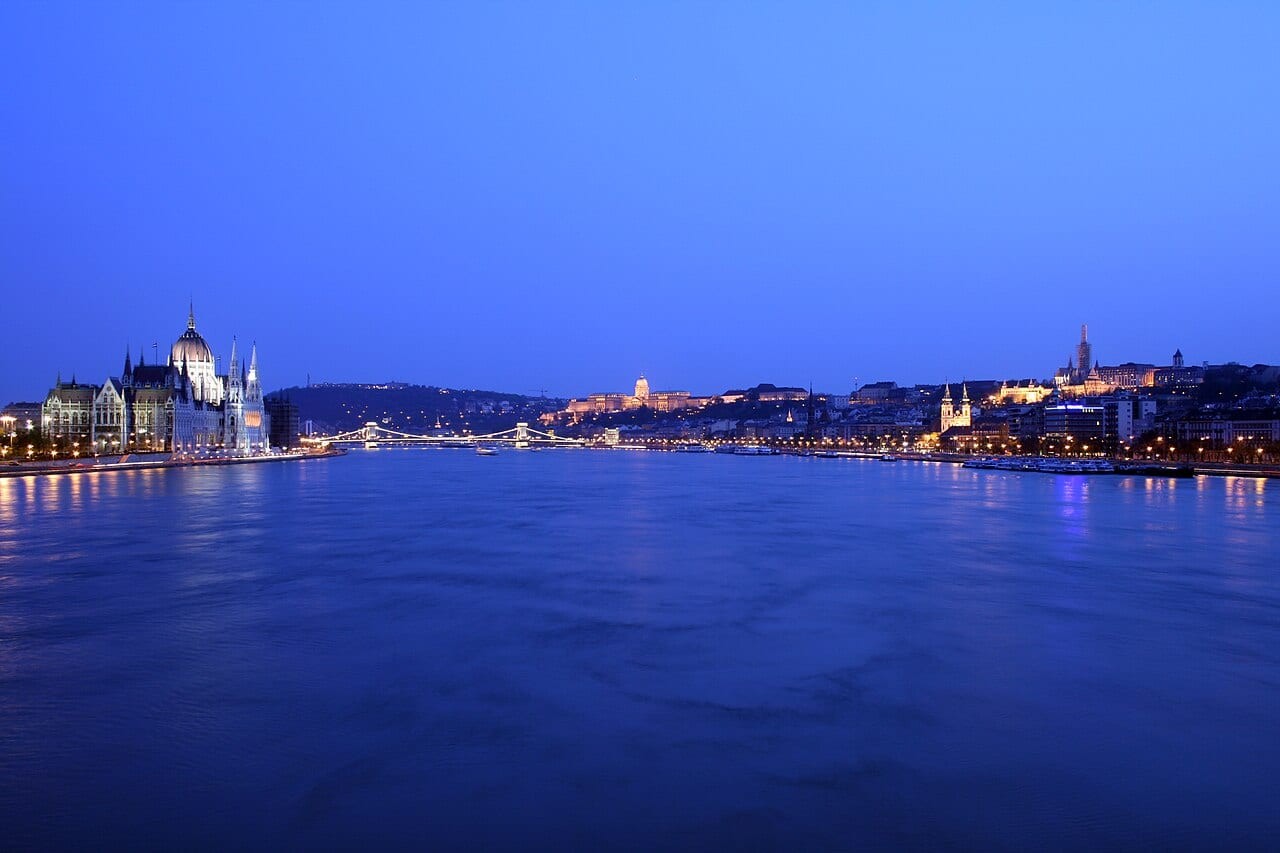

Budapest City Guide
Hungary
Budapest, Hungary's capital (~1.7 million in the city, ~3.3 million metro), straddles the Danube where the historic hills of Buda meet the flat commercial grandeur of Pest. The riverfront panorama, the neo-Gothic Parliament, the Buda Castle Quarter and the Danube embankments, is a UNESCO World Heritage Site, and Andrássy Avenue with its 1896 M1 metro (continental Europe's first underground) was added in 2002. Buda is leafy, hilly and residential; Pest is the dense, walkable urban core where commerce, nightlife and the bulk of the apartment stock concentrate. The city is the world's de-facto 'thermal-bath capital', sitting on 100+ hot springs that feed historic baths (Széchenyi, Gellért, Rudas), a year-round tourism driver behind one of Central Europe's strongest short-stay rental markets. Tourism, EU membership and comparatively low entry prices have made inner Pest a magnet for both lifestyle buyers and yield-seekers. Critically, Hungary uses the forint, NOT the euro, so euro-denominated returns carry currency risk. The market is in regulatory transition: a citywide moratorium on new short-term-rental registrations runs through 2026, District VI has enacted Hungary's first outright Airbnb ban (effective 1 January 2026), and the EU's STR registration regime applies from 20 May 2026. Note also that Hungary's Guest-Investor 'golden visa' no longer includes a direct residential-property option (the €500,000 route was abolished on 15 January 2025), buying an apartment does NOT grant residency. Prices have nonetheless risen sharply, Budapest was among Central Europe's fastest-appreciating capital markets in 2025.
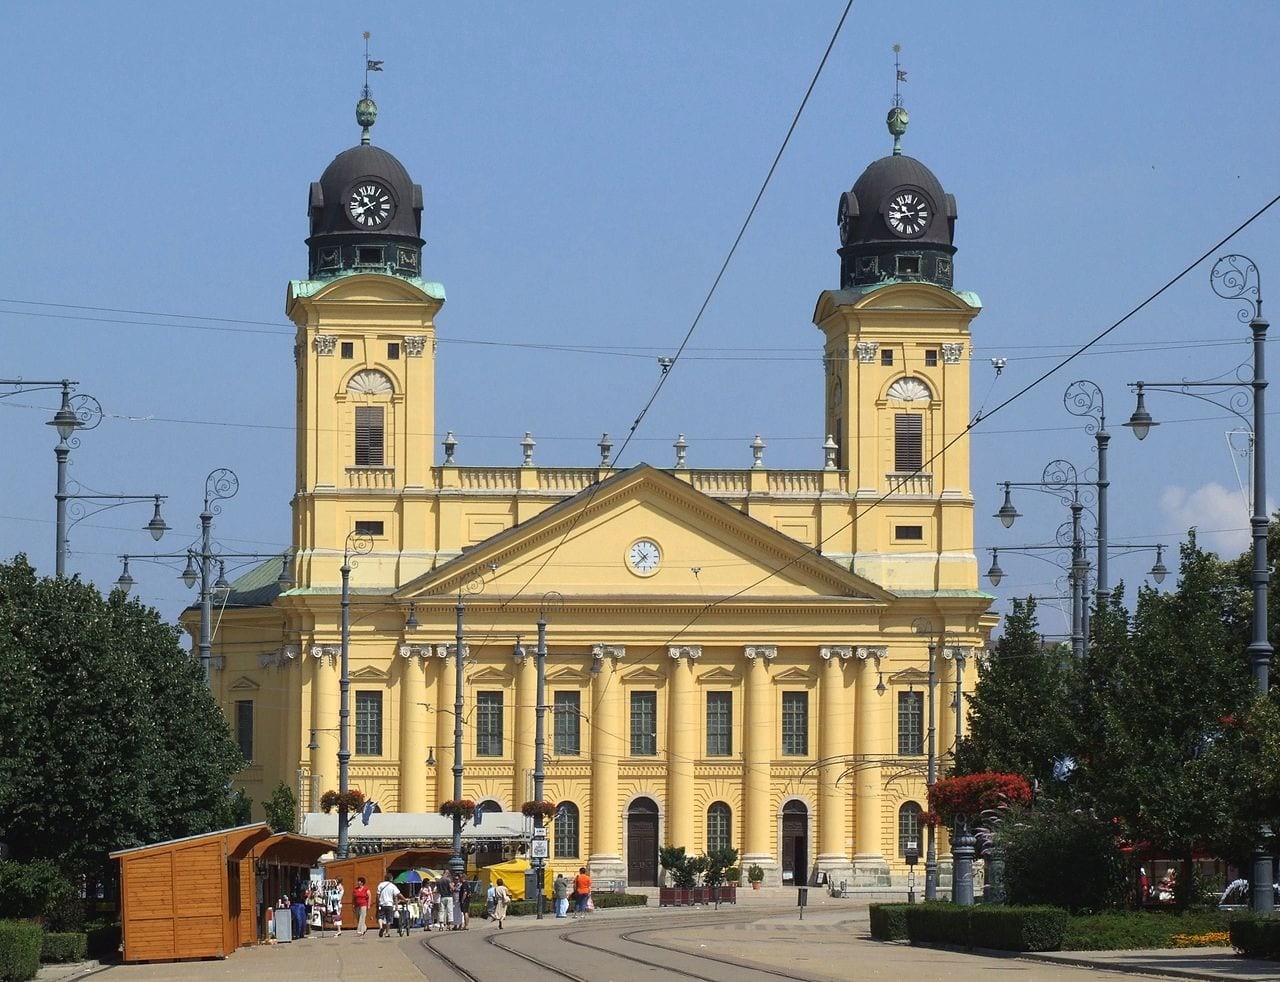
Debrecen City Guide
Hungary
Hungary's second-largest city and the capital of the Northern Great Plain, Debrecen has transformed from a historic university and church town into one of Central Europe's most dynamic industrial-investment stories. The catalyst is BMW: the carmaker's roughly EUR 2 billion iFactory plant, the company's newest, producing the all-electric Neue Klasse iX3, officially opened in late 2025, creating more than 2,000 jobs and triggering a wave of supplier investment and housing demand. With a population around 200,000, Debrecen remains markedly more affordable than Budapest, with average prices near HUF 882,000 (about EUR 2,200) per square metre, though brick-apartment values recently crossed the symbolic one-million-forint mark. The wider Northern Great Plain region led Hungary on price growth in 2025, posting annual gains of roughly 13-17% on the back of industrial investment. Rental yields in Debrecen are among the most attractive in Hungary, with the broader market averaging around 5% and larger or well-located units reaching 6% or more. Demand is anchored by the University of Debrecen, one of the country's largest, the major teaching hospital, and the new automotive workforce. As a forint market, Debrecen carries currency considerations for foreign buyers but offers genuine industrial-led upside.
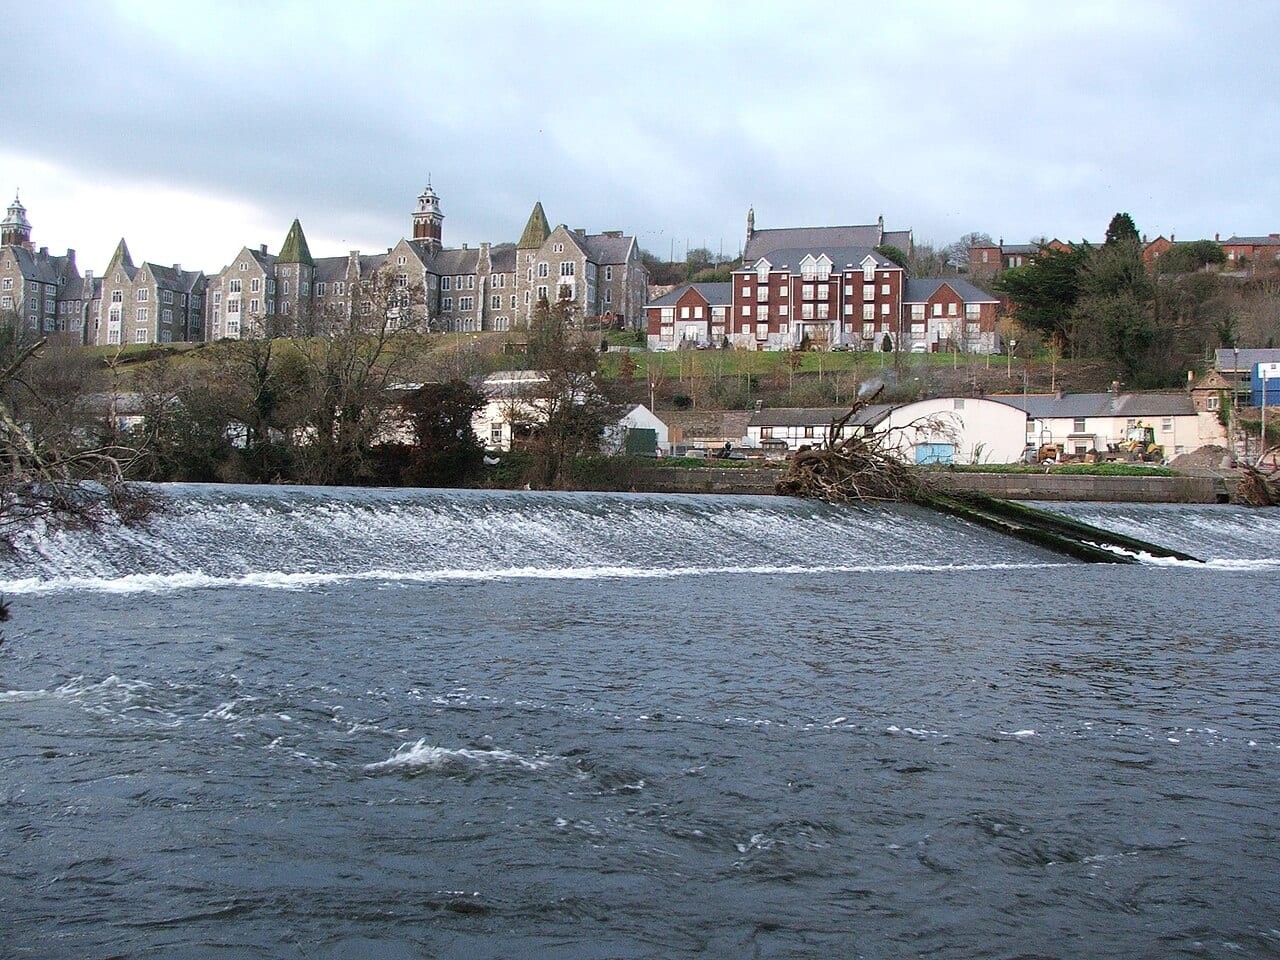

Cork City Guide
Ireland
Ireland’s second city and the capital of the south-west, Cork has become one of the country’s most compelling investment markets, combining a fast-growing tech and pharma employment base with entry prices well below Dublin’s. Global names including Apple (whose European HQ is in Cork), Pfizer, Stryker, and a cluster of pharmaceutical manufacturers anchor a high-wage economy that is drawing population and pushing rents higher. Cork city house prices rose around 7.4% in the year to late 2025 (with the wider South-West region up 9.6% in October 2025), and the average Cork city home now costs roughly €361,500. Crucially, Cork carries some of the strongest rental yields of any major Irish city: city-centre apartments and studios reach gross yields in the region of 7%, well ahead of comparable Dublin returns, though yields fall sharply toward 3% on larger suburban family houses. Income is underpinned by an exceptionally tight rental market, Irish rental availability hit a near-twenty-year low in early 2026, just two-fifths of the 2015–19 average. The Docklands regeneration and continued FDI-driven jobs growth give Cork a clear catch-up narrative versus the capital. With strong fundamentals but a high-yield headline that reflects scarcity and a structural housing shortage, Cork rewards selective, location-led buying.
Dublin
Ireland
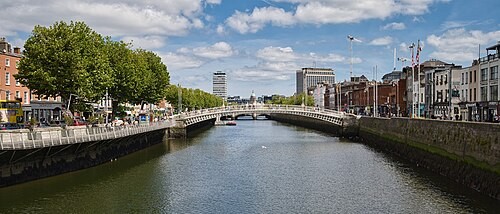
Dublin is Ireland's capital and the only English-speaking capital fully inside the EU and Eurozone post-Brexit -- a structural advantage that has anchored a decade of strong economic, demographic, and property market growth. The city is home to the European HQs of Google, Meta, Apple, Microsoft, Stripe, LinkedIn, TikTok, Pfizer, and most of US Big Pharma, alongside a thriving domestic finance and professional services sector. Central residential (Ballsbridge, Donnybrook, Sandymount, Rathmines, Ranelagh, City Centre) commands EUR 6,000-11,500 per square metre, with gross yields of 4.5-6.5%. Dublin's housing supply consistently runs 30-40% below demand -- one of the worst structural shortfalls in any developed-world capital -- supporting double-digit rental growth in 2024-25. For international buyers, Dublin offers Eurozone safety with English as the primary language, deep institutional tenant demand from US tech and pharma multinationals, and one of Europe's most resilient capital growth profiles. The catch: prices have already run 80%+ since 2014, transaction costs are 5-7%, and the rental sector is tightly regulated (Rent Pressure Zones cap most rent increases at 2% or HICP).

Haifa City Guide
Israel
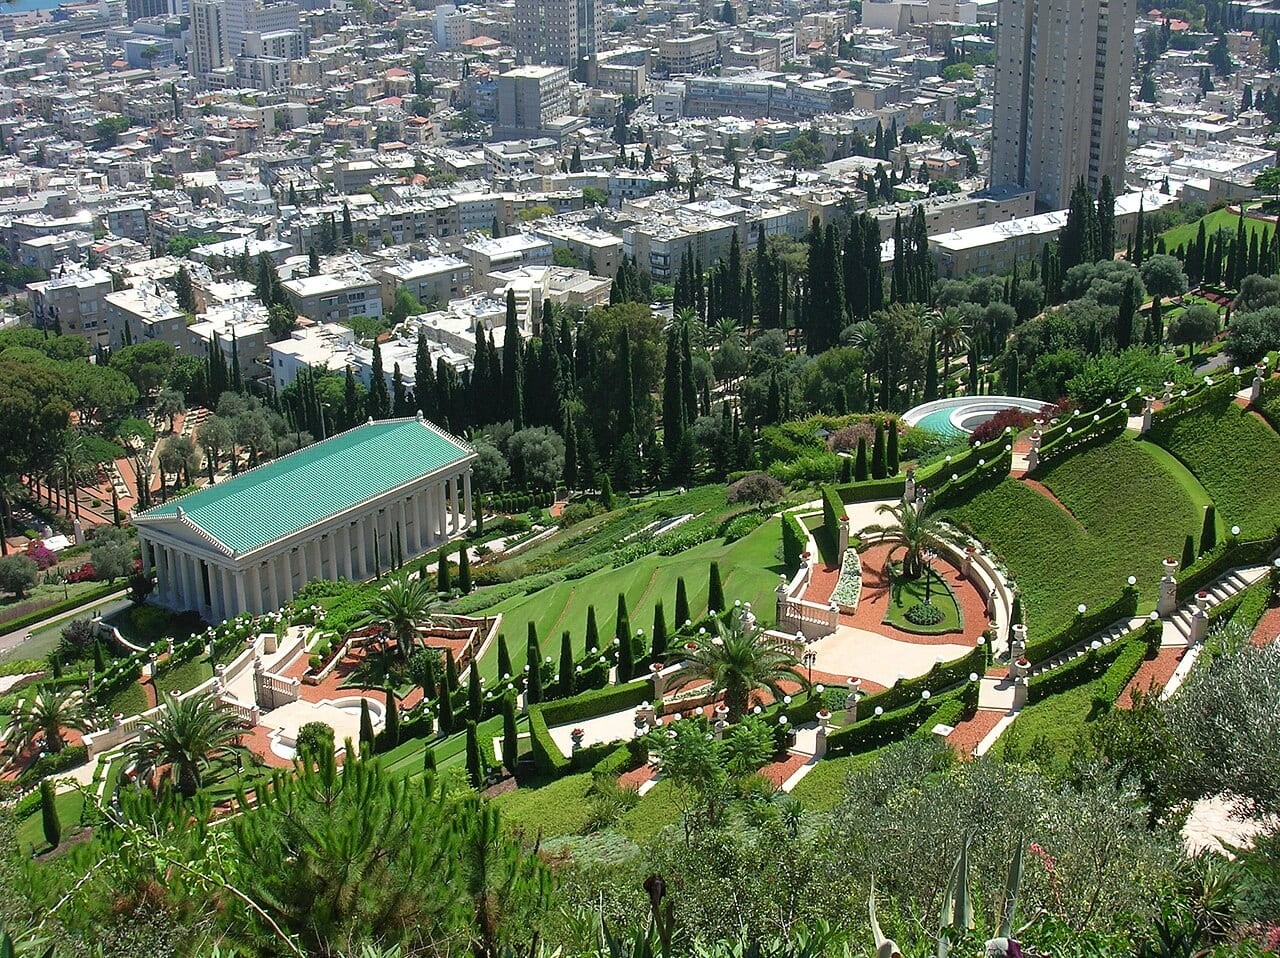
Israel's third-largest city and the economic anchor of the north, Haifa cascades down the slopes of Mount Carmel to a major Mediterranean port, blending a deep-water shipping and logistics hub with one of the country's most important technology and academic ecosystems. The Technion (Israel Institute of Technology) and the University of Haifa underpin a research-driven economy that hosts R&D centres for Intel, Google and Amazon, while the city is celebrated for the UNESCO-listed Baha'i Gardens and a famously mixed, tolerant social fabric. With a population around 285,000, Haifa is the most affordable of Israel's major cities, with prices roughly ILS 12,000-25,000 per square metre. The market showed strong momentum in early 2025: average residential prices rose about 9.4% year-on-year in Q1 to ILS 2.16 million, with price per square metre up 10.8% and transaction volume up 14.1%. Gross rental yields, while modest by global standards, are attractive for Israel at around 3.4-3.9% citywide, rising higher near the Technion where student-housing occupancy exceeds 97%. Key districts include the upscale Carmel Center, the gentrifying Hadar and German Colony, and the Technion-adjacent Neve Sha'anan, giving investors a more accessible entry into Israel's resilient housing market than Tel Aviv.

Tel Aviv City Guide
Israel
Tel Aviv-Yafo is the Mediterranean economic and cultural capital of Israel and the heart of 'Startup Nation', a dense tech and venture-capital hub where glass towers sit beside the UNESCO-listed 'White City' of 4,000+ 1930s Bauhaus buildings. Fronting a scarce, supply-constrained beachfront, it is consistently ranked among the world's most expensive cities, with the highest residential prices in the Middle East. For investors it is a global-city, capital-growth and lifestyle market: prices average roughly €15,750/m² citywide and are steadying after the wartime slump, with the new metro reshaping accessibility. Yields are thin (~2.5–3.5%), so the case is scarcity-driven appreciation rather than income.

Bologna City Guide
Italy
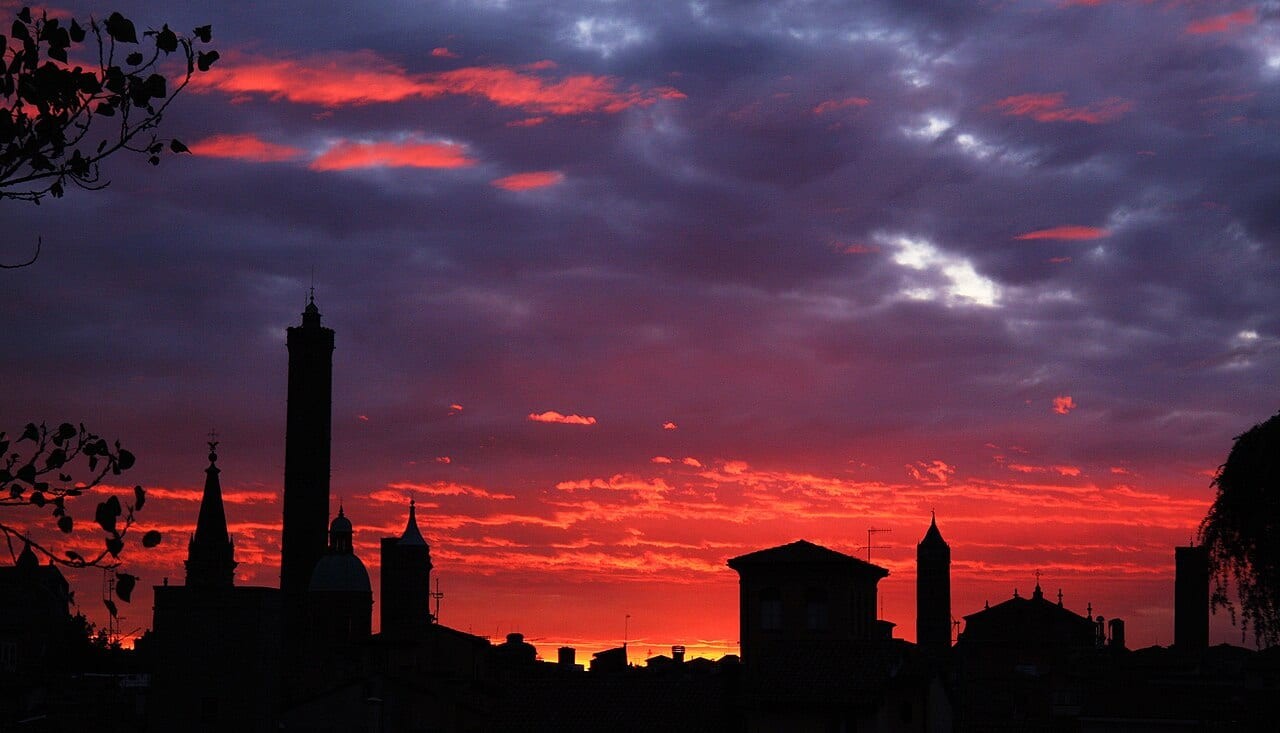
Bologna, capital of Emilia-Romagna and home to the world's oldest university, is one of Italy's most resilient and rental-driven property markets. The city of roughly 391,000 (with more than a million in its metropolitan province) sits at the heart of the national rail network, two hours from both Milan and Florence, and combines a perfectly preserved medieval Centro Storico (Europe's largest network of porticoes) with a diversified economy spanning education, research, advanced manufacturing and a globally renowned food cluster. For investors the defining feature is rental demand: a vast student population and constant inflow of researchers and professionals keep vacancies minimal, with landlords often fielding multiple applications within hours of listing. Average asking prices reached roughly 3,600-3,818 euros per square metre by 2026, up around 6% year-on-year and the highest in years, while gross yields range from about 3% in the priciest pockets to above 7% in higher-yield neighbourhoods. Bologna is forecast among Italy's fastest-growing markets for 2026, with university districts expected to see the strongest rent growth. As a Eurozone city it offers legal and currency stability, but investors should weigh real headwinds: Italy's lengthy purchase and bureaucratic processes, rising prices that compress yields at the top end, and growing regulatory attention to short-term rentals in the historic centre.